Introduction to Disability Insurance and Income Protection
Disability insurance coverage and income protection are essential financial safety tools designed to protect individuals from loss of income when they are unable to work due to illness, injury, or medical conditions. Many people assume that disability only happens in extreme cases, but in reality, millions of workers experience short-term or long-term disabilities every year.
Without proper protection, a sudden inability to work can quickly lead to financial stress, unpaid bills, and long-term debt. This is why understanding disability insurance coverage and how income protection insurance works is critical for employees, freelancers, and self-employed individuals alike.
This guide explains everything you need to know, including how coverage works, what it includes, types of policies, benefits, exclusions, and how to choose the right plan.
What Is Disability Insurance Coverage?
Disability insurance coverage is a type of insurance that replaces a portion of your income if you are unable to work due to a qualifying disability. It ensures that you can continue to pay your living expenses even when you are temporarily or permanently unable to earn a salary.
There are two main categories:
1. Short-Term Disability Insurance
Short-term disability insurance typically covers a portion of your income for a limited period, such as:
- 3 months
- 6 months
- Up to 1 year
It is often used for temporary conditions like:
- Surgery recovery
- Pregnancy complications
- Minor injuries
- Short-term illnesses
2. Long-Term Disability Insurance
Long-term disability insurance provides income replacement for extended periods, sometimes lasting:
- Several years
- Until retirement age (65 or older)
It covers more serious conditions such as:
- Chronic illnesses
- Severe injuries
- Long-term physical or mental disabilities
What Is Income Protection Insurance?
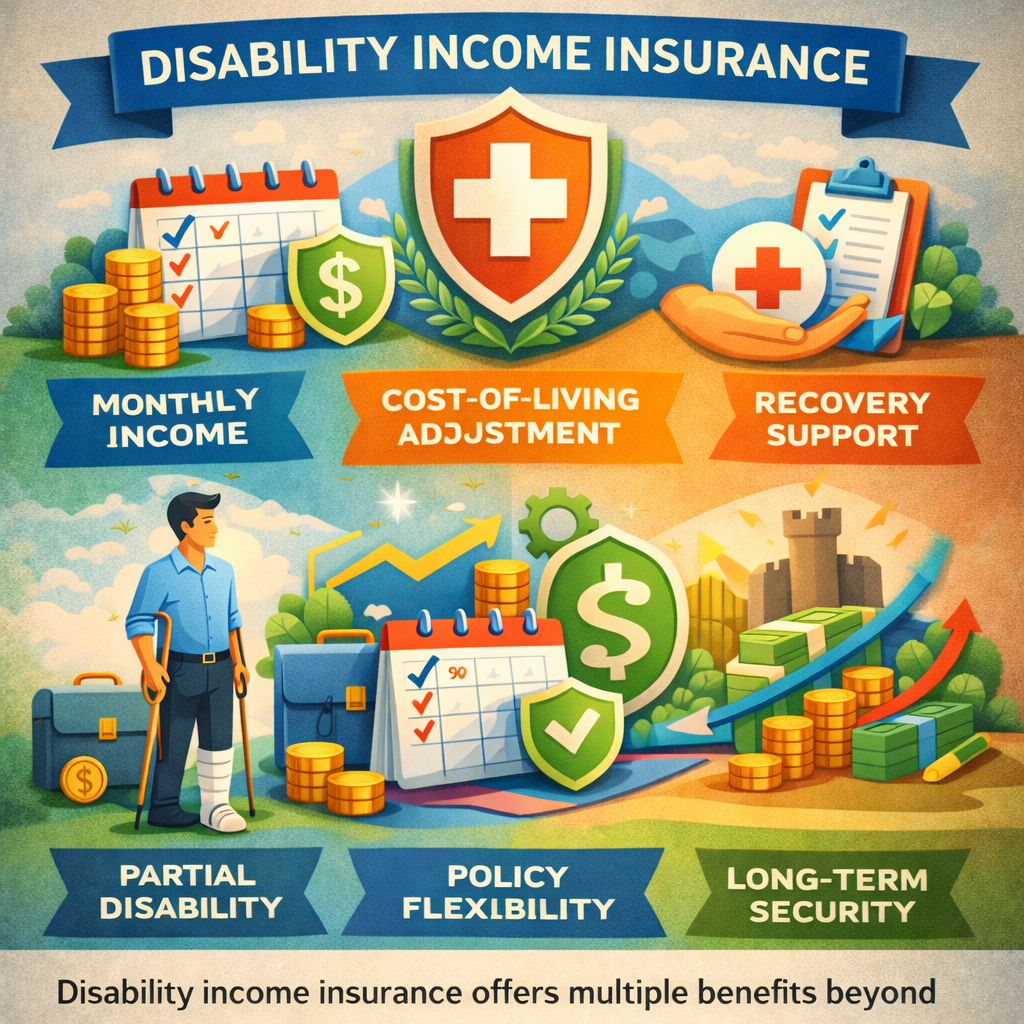
Income protection insurance is similar to disability insurance but is often more flexible. It is designed to replace a percentage of your income if you are unable to work due to illness or injury.
Typically, income protection policies cover:
- 50% to 70% of your monthly income
- Partial disability (reduced working capacity)
- Rehabilitation support
- Return-to-work programs
Unlike traditional disability insurance, income protection is widely used by:
- Freelancers
- Self-employed professionals
- Small business owners
- Contract workers
Why Disability Insurance Coverage Is Important
Many people underestimate the financial risk of losing their ability to work. Statistics show that disability is more common than most people think, and it can happen at any age.
Key reasons why coverage is essential include:
1. Income Replacement Security
Your salary is often your primary financial resource. Disability insurance ensures you still receive income even when you cannot work.
2. Protection Against Medical Costs
While health insurance covers medical treatment, it does not cover lost income or daily expenses like rent, mortgage, or groceries.
3. Financial Stability for Families
If you are the main income provider, disability coverage protects your family’s financial future.
4. Peace of Mind
Knowing that your income is protected reduces stress and allows you to focus on recovery.
How Disability Insurance Works
The process of disability insurance coverage typically follows these steps:
- Policy Purchase – You choose a plan based on income, occupation, and coverage needs.
- Premium Payments – You pay monthly or annual premiums.
- Claim Filing – If you become disabled, you submit medical proof.
- Evaluation Period – The insurer reviews your condition.
- Benefit Payments – If approved, you receive monthly income replacement.
Most policies require a waiting period (also called elimination period), which can range from:
- 14 days (short-term policies)
- 30 to 180 days (long-term policies)
What Does Disability Insurance Cover?
Coverage varies depending on the policy, but most plans include:
Covered Conditions:
- Physical injuries
- Serious illnesses (cancer, stroke, heart disease)
- Mental health conditions (in some policies)
- Occupational injuries
Additional Benefits:
- Partial disability benefits
- Rehabilitation support
- Vocational training
- Return-to-work assistance
However, coverage may differ depending on insurer and plan type.
Common Exclusions in Disability Insurance
Not all situations are covered. Common exclusions include:
- Self-inflicted injuries
- Injuries from illegal activities
- Pre-existing conditions (in some cases)
- Cosmetic surgery recovery
- Injuries from high-risk hobbies (depending on policy)
It is important to carefully read policy terms before purchasing coverage.
Who Needs Income Protection Insurance?
Income protection is not only for high-risk professions. It is suitable for almost everyone who relies on monthly income.
Ideal candidates include:
- Office workers
- Healthcare professionals
- Construction workers
- Freelancers
- Gig economy workers
- Self-employed entrepreneurs
Even desk jobs carry risks such as repetitive strain injuries, stress-related illnesses, or accidents outside of work.
How Much Disability Coverage Do You Need?
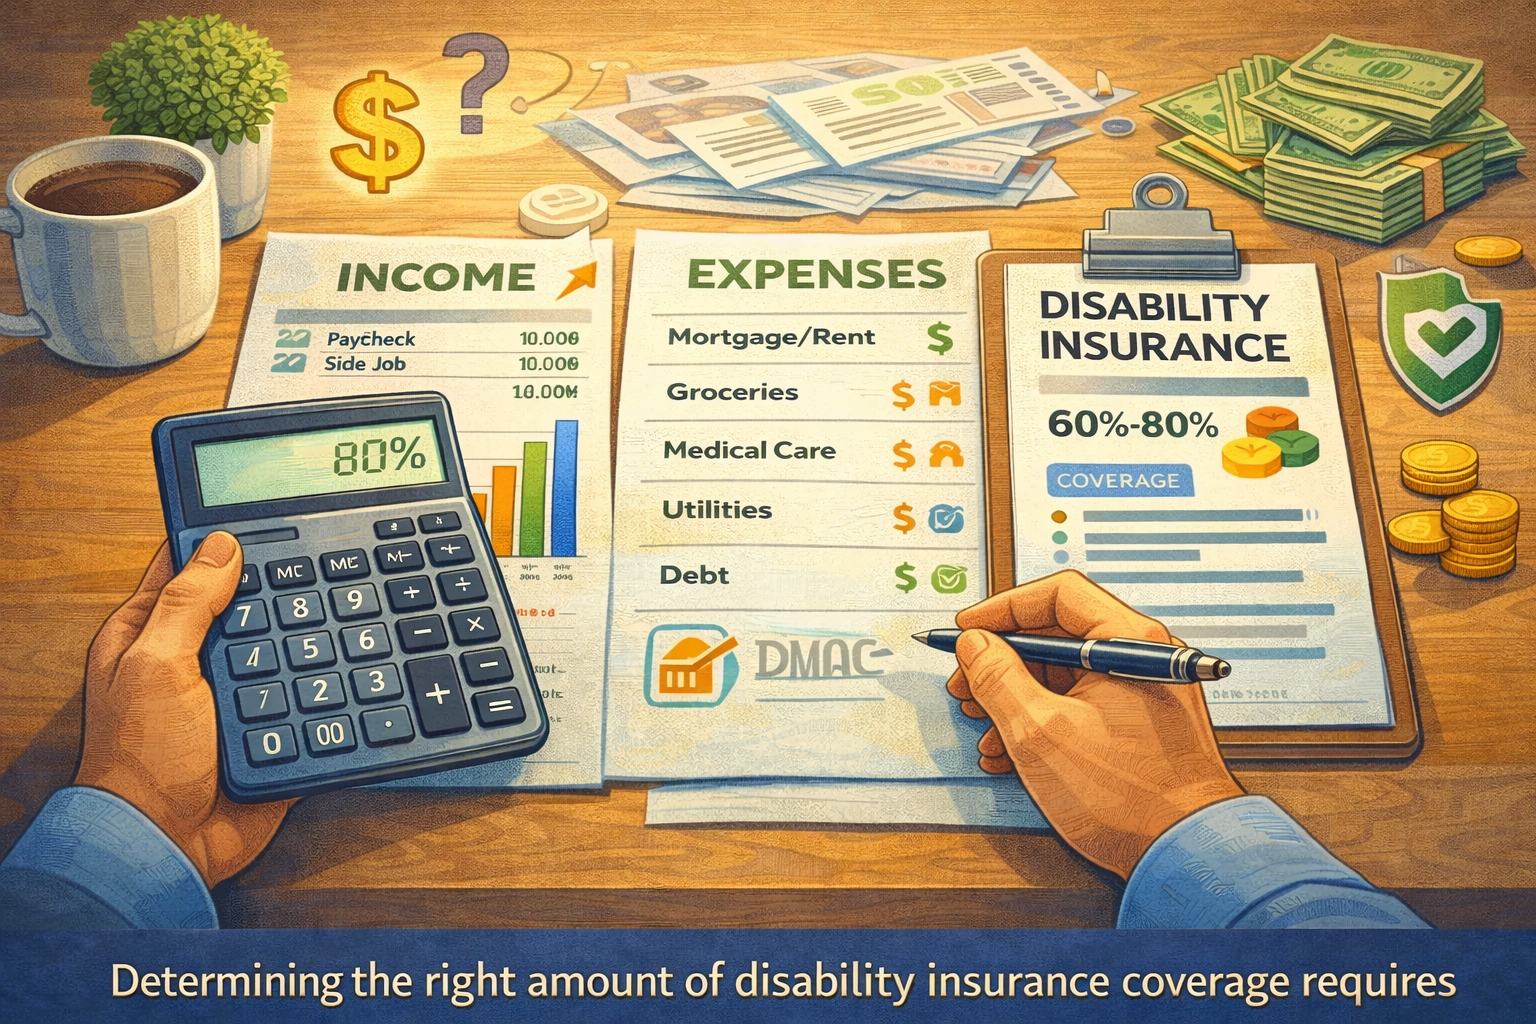
A general guideline is to replace:
- 60% to 80% of your monthly income
Factors to consider:
- Monthly expenses (rent, mortgage, bills)
- Family dependents
- Savings and emergency funds
- Existing employer benefits
If you already have partial coverage from your employer, you may only need supplemental insurance.
Cost of Disability Insurance
The cost of disability insurance depends on several factors:
- Age
- Occupation risk level
- Health condition
- Coverage amount
- Waiting period length
Generally:
- Low-risk jobs (office workers): lower premiums
- High-risk jobs (construction, manual labor): higher premiums
Income protection insurance may cost between 1% and 3% of annual income depending on coverage.
Tips for Choosing the Right Policy
When selecting disability insurance or income protection, consider:
1. Coverage Percentage
Choose a plan that covers enough of your income to maintain your lifestyle.
2. Waiting Period
Shorter waiting periods mean faster payments but higher premiums.
3. Benefit Duration
Longer benefit periods offer better security.
4. Policy Definitions
Check whether the policy uses:
- Own-occupation definition (best coverage)
- Any-occupation definition (more restrictive)
5. Add-On Benefits
Look for optional riders like inflation protection or partial disability coverage.
Conclusion
Disability insurance coverage and income protection are essential financial tools that safeguard your income in case of illness or injury. Whether you are an employee, freelancer, or business owner, having the right protection ensures financial stability and peace of mind.
By understanding how disability insurance works, what it covers, and how to choose the right plan, you can make informed decisions that protect both your income and your future.
States That Pay You Directly
Twelve states and the District of Columbia run some form of disability or paid-family-leave program funded by payroll tax. If you live in one, you already own a slice of short-term disability coverage – and it changes what private policy you should buy.
Approximate 2025-2026 figures – verify the current cap with the state agency before you plan around it.
| State | Program | Benefit level | Duration | Approx. max weekly |
|---|---|---|---|---|
| California | SDI | 60-70% of wages | Up to 52 weeks | $1,600-$1,700 |
| New York | DBL + PFL | 50% (DBL), 67% (PFL) | 26 weeks DBL / 12 weeks PFL | $170 DBL / $1,200 PFL |
| New Jersey | TDB + FLI | 85% of wages | 26 weeks TDB / 12 weeks FLI | $1,050-$1,100 |
| Rhode Island | TCI | 60-85% of wages | 30 weeks | $1,000-$1,100 |
| Washington | PFML | 90% then 50% of wages | 12-16 weeks | $1,500-$1,600 |
| Massachusetts | PFML | 80% then 50% of wages | 20-26 weeks | $1,200-$1,300 |
| Connecticut | PFML | 95% then 60% of wages | 12-16 weeks | $900-$1,000 |
| Colorado | FAMLI | 90% then 50% of wages | 12-16 weeks | $1,300-$1,400 |
| Oregon | Paid Leave | 100% then 50% of wages | 12-14 weeks | $1,500-$1,600 |
| Maryland | Paid Family Leave | Phasing in from 2028 | Up to 12 weeks | TBD |
How State Benefits Interact With Private DI
State programs cover the first year. Private insurance covers the decade after it.
| Situation | State benefit | Private DI effect |
|---|---|---|
| Own-occupation claim, CA resident | SDI pays ~70% up to the cap | Most individual policies offset SDI; some do not |
| Employer group LTD in NJ | TDB pays 85% of wages | Group LTD offsets TDB dollar for dollar |
| Pregnancy in WA | PFML pays 12-16 weeks | Private DI usually excludes normal pregnancy anyway |
| Self-employed in MA | PFML covers self-employed who opt in | Opting in reduces the private coverage needed for short claims |
| Long claim, 3+ years | State programs end at 12-52 weeks | Private DI is what covers years 2-30 |
What This Means for What You Buy
- In a state program state, you can take a longer elimination period (90-180 days) because the state covers the first months, and spend the savings on a longer benefit period or COLA.
- Skew your private policy toward the long tail. A program that pays 52 weeks does nothing for a three-year claim, which is the claim that bankrupts households.
- Check the offset language. If your individual policy offsets state benefits, the state program effectively pays the insurer, not you – which is a reason to look for a non-offsetting contract.
- Self-employed: opt-in deadlines for state programs are usually annual. Miss it and you are outside the system for a full year.
The Four States With No Program and No Safety Net
Most states have no disability program at all. In those states, a private policy is the only income protection between your savings and SSDI – and SSDI takes months to approve, denies most first applications, and pays a modest, capped amount.
That asymmetry is the practical argument for individual coverage in the other 38 states: the public system is either absent or short, and the long claim is precisely the one nobody can self-fund.
Frequently Asked Questions
Does my state have disability insurance?
Twelve states plus DC run disability or paid-family-leave programs: CA, NY, NJ, RI, WA, MA, CT, CO, OR, HI, PR and MD (phasing in). The rest have no wage-replacement program, only workers compensation for work injuries.
Do state disability benefits reduce my private insurance?
Often yes, but it depends on the policy. Group LTD almost always offsets state benefits; individual policies vary, and some ignore them entirely. The offset clause decides.
How much does state disability pay?
Typically 50-85% of wages up to a weekly cap of roughly $170-$1,700 depending on the state, for 12-52 weeks. The caps matter more than the percentages for middle and high earners.
Can self-employed people join state programs?
Some states allow opt-in with an annual deadline (Massachusetts, Colorado, Oregon, Washington). Miss the deadline and you are outside the program for the year.
Is state disability the same as workers compensation?
No. Workers comp covers work-related injuries only and is employer-funded; state disability programs cover non-work illness and injury and are payroll-tax funded.
What happens after state benefits end?
You rely on private long-term disability, SSDI, or savings. State programs last 12-52 weeks, while the average long-term disability claim lasts about 31 months – the gap is why private LTD exists.
Leave a Reply