Introduction to Disability Insurance and Income Protection
Life is unpredictable. While most people focus on health insurance, life insurance, or retirement planning, one of the most overlooked yet essential forms of financial protection is disability insurance coverage. A sudden illness, accident, or long-term medical condition can prevent you from working and earning income. Without proper protection, even a short period without income can lead to financial instability.
This is where income protection insurance, also known as disability insurance, plays a critical role. It ensures that you continue to receive a portion of your income when you are unable to work due to illness or injury.
Understanding how disability insurance works, what it covers, and how to choose the right policy is essential for long-term financial security.
What Is Disability Insurance?
Disability insurance is a type of coverage that replaces a portion of your income if you become unable to work due to a qualifying medical condition.
It is designed to protect your financial stability when your ability to earn is interrupted.
There are two main types:
1. Short-Term Disability Insurance (STD)
- Covers temporary disabilities
- Usually lasts 3 to 6 months
- Common for recovery from surgery, injury, or short illnesses
2. Long-Term Disability Insurance (LTD)
- Covers extended or permanent disabilities
- Can last several years or until retirement age
- Applies to serious conditions like cancer, neurological disorders, or chronic illness
How Income Protection Works
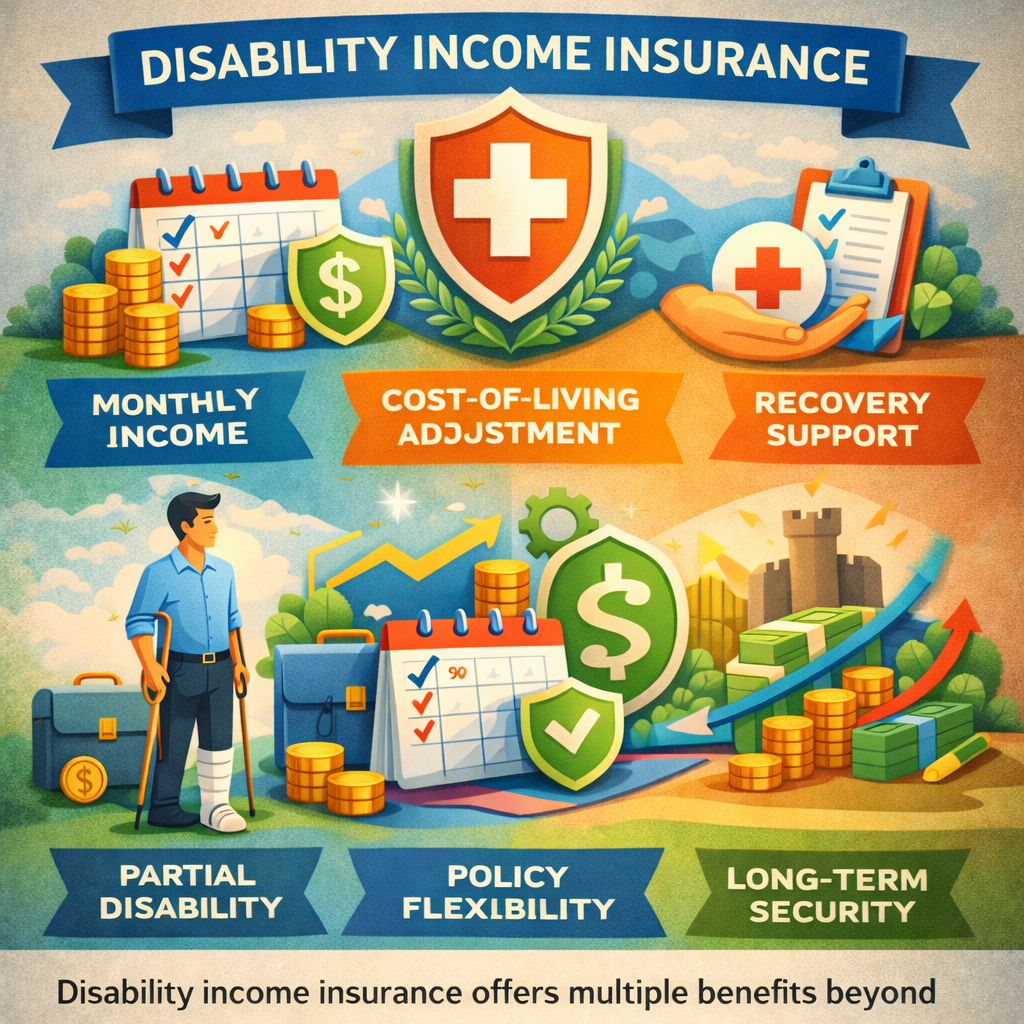
Income protection insurance replaces a percentage of your income—typically 50% to 70% of your salary—if you cannot work.
Key process:
- You pay monthly or annual premiums
- You become disabled due to illness or injury
- You file a claim with your insurance provider
- After approval, you receive monthly benefit payments
These payments help cover essential living expenses such as:
- Rent or mortgage
- Utilities
- Food and groceries
- Transportation
- Medical bills
What Conditions Are Covered?
Disability insurance typically covers both physical and mental health conditions.
Common covered conditions include:
- Back injuries and musculoskeletal disorders
- Cancer
- Heart disease
- Stroke
- Severe depression or anxiety disorders
- Neurological conditions like multiple sclerosis
- Accidents resulting in long-term disability
However, coverage depends on the policy terms and insurer.
Why Disability Insurance Is Important
Many people assume they will never need disability coverage, but statistics show otherwise.
1. Higher risk than you think
Studies show that 1 in 4 workers may experience a disability during their working life.
2. Income is your most important asset
Unlike savings, your ability to earn income is continuous—but only if you are healthy.
3. Savings are not enough
Most people do not have enough emergency savings to survive long-term income loss.
4. Protects your lifestyle
Without income protection, you may be forced to:
- Sell assets
- Take loans
- Reduce living standards
Who Needs Disability Insurance?
Disability insurance is not only for high-risk jobs. It is relevant for almost everyone who depends on income.
You especially need it if you are:
- A salaried employee
- A freelancer or self-employed worker
- A business owner
- The primary income earner in a household
- Working in a physically demanding job
Even office workers are at risk due to chronic illness or mental health conditions.
Key Features to Compare in a Policy
When choosing disability insurance, several important factors must be considered:
1. Benefit amount
The percentage of income replaced (usually 50%–70%).
2. Waiting period (elimination period)
The time before benefits begin (e.g., 30, 60, 90 days).
3. Benefit duration
How long payments continue (months, years, or until retirement).
4. Definition of disability
- Own occupation: cannot perform your specific job
- Any occupation: cannot perform any job
“Own occupation” policies are generally more favorable.
5. Premium cost
Monthly payments depend on age, health, and occupation.
Common Mistakes People Make
1. Thinking employer coverage is enough
Many employers offer limited short-term coverage that may not fully replace income.
2. Ignoring mental health coverage
Some policies exclude or limit psychological conditions.
3. Underestimating risk
People often believe disability will never happen to them.
4. Choosing cheapest policy only
Low-cost plans may have weak coverage or strict conditions.
Disability Insurance vs. Life Insurance
These two are often confused but serve different purposes:
| Feature | Disability Insurance | Life Insurance |
|---|---|---|
| Coverage | Income loss due to disability | Death benefit |
| Beneficiary | Policyholder | Family/dependents |
| Purpose | Replace income while alive | Financial support after death |
Both are important for complete financial planning.
How to Choose the Right Income Protection Plan
Choosing the right policy depends on your lifestyle and financial situation.
Step-by-step guide:
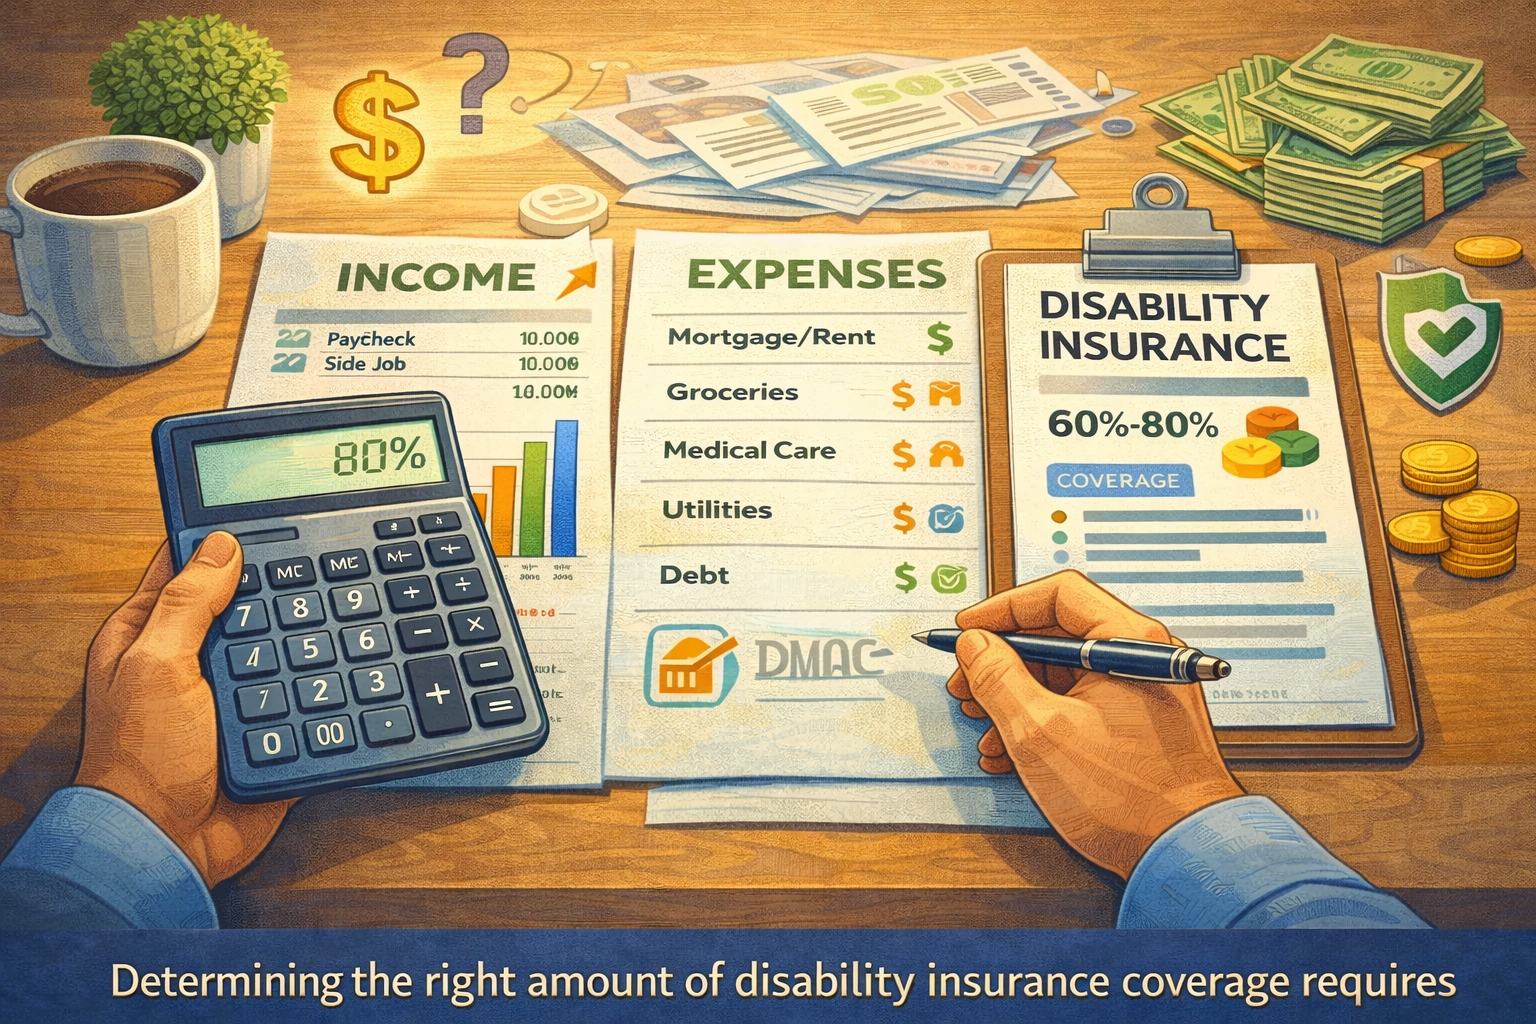
- Evaluate your monthly expenses
- Calculate income replacement needs
- Compare insurance providers
- Check policy exclusions carefully
- Choose a balance between cost and coverage
A good policy should provide stability without financial strain.
The Future of Income Protection Insurance
The insurance industry is evolving with technology.
Trends include:
- AI-based risk assessment
- Faster claim processing
- Personalized insurance plans
- Digital-only policy management
- Integration with health tracking devices
These innovations make disability insurance more accessible and efficient.
Conclusion
Disability insurance coverage and income protection are essential components of financial security. While many people focus on saving and investing, protecting your income is equally important. A sudden disability can disrupt your life financially, but the right insurance plan ensures stability and peace of mind.
Whether you are an employee, freelancer, or business owner, having income protection means you are prepared for life’s uncertainties. It is not just insurance—it is financial resilience.
The Protection Ladder, in the Right Order
Disability insurance is one rung on a ladder, and buying rungs out of order is the most common financial planning error. The order is set by probability times severity, not by how the products are sold.
Disability sits above life insurance because the probability is higher and the cost is paid while you are alive.
| Rung | Product | What it protects against | Funding priority |
|---|---|---|---|
| 1 | Emergency reserve (3-6 months) | Job loss, small shocks | Before anything else |
| 2 | Health insurance | Medical costs, the leading cause of bankruptcy | Immediate |
| 3 | Disability insurance | The 30-40% chance of a 90+ day disability during a career | Immediate, once reserve exists |
| 4 | Term life insurance | Premature death with dependents | When someone depends on your income |
| 5 | Umbrella liability | A judgment above auto or home limits | Once you have assets to protect |
| 6 | Long-term care | Extended care costs in later life | Age 50-60, or when assets justify it |
How the Ratios Fit Together
Together these consume roughly 3-6% of income – less than most households spend on subscriptions and dining.
| Coverage | Typical target | Cost as % of income | What it replaces |
|---|---|---|---|
| Emergency fund | 3-6 months of expenses | Opportunity cost only | Short shocks |
| Disability | 50-70% of income | 1-3% | Earned income |
| Term life | 10-12x income, if dependents | 0.5-1% | Income for survivors |
| Umbrella | $1M above underlying limits | 0.1-0.3% | Assets above policy limits |
| Long-term care | $150-$250/day benefit | 1-2% after 50 | Care costs, not income |
Where Disability Fits With Life Insurance
- Life insurance pays when you die; disability pays when you do not. The second scenario is three to four times more likely during your working years.
- They are not substitutes. A $500,000 term policy does nothing for a 45-year-old who cannot work for three years but will live another forty.
- Riders are not a plan. A disability income rider on a life policy typically pays a small monthly amount for a short period – useful as a supplement, not as core coverage.
- Order of purchase for a new parent: reserve, health, disability, term life, umbrella. Buying life first and skipping disability inverts the risk.
A Five-Step Allocation for a Household Earning $120,000
- Fund a $18,000-$27,000 emergency reserve (3-6 months of $4,500 essential spending).
- Confirm health coverage and an HSA if eligible – medical costs drive most disability-related bankruptcies.
- Buy disability coverage to 60% of income, own-occupation if the budget allows, 90-day elimination period.
- Add 10-12x income in 20-30 year term life if anyone depends on the income.
- Add a $1M umbrella policy once net worth exceeds auto and home liability limits.
Frequently Asked Questions
Should I buy disability insurance or life insurance first?
Disability, if you must choose. A working-age person is far more likely to be disabled for 90+ days than to die, and the financial consequences arrive while you are still paying the bills.
How does disability insurance fit into a financial plan?
It protects the income that funds every other goal. Without it, retirement contributions, mortgage payments and education savings all stop at once – which is why it sits directly above health insurance in priority.
How much of my income should go to protection products?
Roughly 3-6% total across disability, term life, umbrella and long-term care. Disability alone typically runs 1-3% of gross income.
Is a disability rider on a life policy enough?
No. Those riders usually pay a small monthly benefit for a limited period. Core disability coverage needs a standalone policy with a definition and duration you chose deliberately.
Do I need disability insurance if I have no dependents?
Yes – you still have rent, debt and future earning capacity to protect. Without dependents you may need a shorter benefit period, but not zero coverage.
Can I self-insure instead?
Only with substantial liquid assets – roughly 30 times your annual essential spending. Below that, a long disability consumes savings faster than any investment can replace them.
Leave a Reply