Your ability to earn is almost certainly your largest financial asset — larger than your home, larger than your retirement account, and unlike either of them, completely uninsured by default. A 35-year-old earning $80,000 has roughly $1.5 million of future earnings ahead of them. Very few people insure a house worth that much and leave the income that pays for it unprotected.
But “buy disability insurance” is not actionable until you know how much. Too little and the benefit does not cover your bills. Too much and the insurer will not issue the policy — every carrier caps the benefit at a percentage of income, and asking above the cap gets your application declined or reduced.
This page gives you three ways to calculate the number, a table of worked examples across income levels, and the rules that determine what an insurer will actually approve.
Why getting the number right matters more than the price
Disability underwriting is financial as well as medical. Insurers limit benefits to a replacement ratio — usually 60% to 70% of income — on the reasoning that a policy paying 100% removes any incentive to return to work. Two failure modes follow:
- Under-insuring. A policy replacing 40% of income when your fixed costs are 65% of income does not solve the problem it was bought to solve. You pay premiums for years and still face a shortfall at claim time.
- Over-applying. Requesting a benefit above the carrier’s issue limit gets the application reduced or declined, and a decline is recorded. The correct approach is to apply at the maximum the carrier will write for your income and occupation, which is almost always the right amount anyway.
Method 1: income replacement (the standard approach)
This is what most agents use, and it is the fastest to compute.
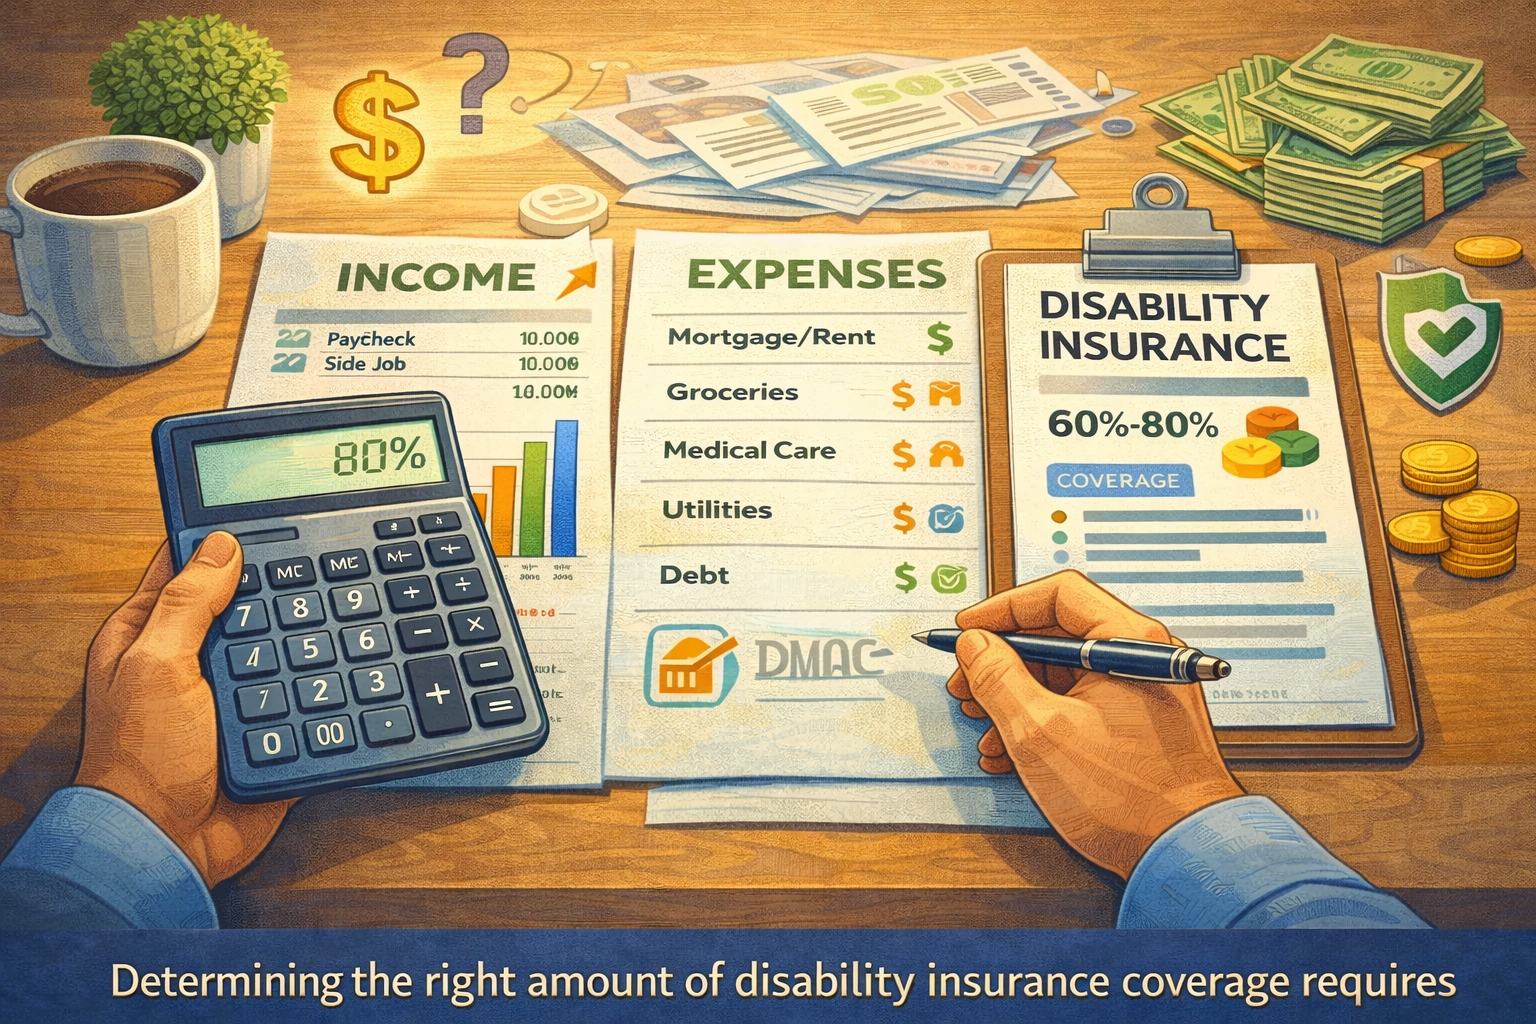
Monthly benefit = gross monthly income × replacement rate
Then adjust for two things: whether the benefit is taxable, and whether you already have group coverage whose payout will be offset.
| Input | Typical value | Note |
|---|---|---|
| Replacement rate | 60%–70% | Insurers rarely exceed 70%; high earners are often capped lower |
| Tax treatment | Tax-free if you paid premiums with after-tax dollars | A tax-free 60% can equal a taxable 75–80% |
| Group coverage offset | Subtracted from the individual benefit | Most individual policies coordinate with group LTD |
| Social Security offset | Sometimes subtracted | Check the policy’s “other income” clause |
Worked example: $80,000 salary is $6,667 a month. At a 60% replacement rate the benefit is $4,000 a month. If an employer group LTD already pays 60% of base up to a $5,000 cap, an individual policy on top may pay little or nothing until the group benefit is exhausted — which is why high earners buy individual coverage to raise the cap, not the percentage.
Method 2: human life value (what your earnings are worth)
This method values your remaining earning capacity and is the one that makes the “your income is your biggest asset” argument concrete.
Human life value = annual income × remaining working years
Adjust downward for personal consumption (typically 25–30% of income is spent on yourself) and for the time value of money.
| Age | Annual income | Years to 65 | Gross earning capacity | Net of 30% self-consumption |
|---|---|---|---|---|
| 30 | $60,000 | 35 | $2,100,000 | $1,470,000 |
| 35 | $80,000 | 30 | $2,400,000 | $1,680,000 |
| 45 | $120,000 | 20 | $2,400,000 | $1,680,000 |
| 55 | $150,000 | 10 | $1,500,000 | $1,050,000 |
This number is not the coverage amount — it is the asset at risk. It explains why the premium is trivial relative to the exposure: $1,500 a year to protect $1.7 million of earning capacity is not an expense, it is a hedge.
Method 3: expense and debt coverage (what you actually need to pay)
The most grounded method, and the one that answers “how much is enough” rather than “how much can I buy.” It is also the method that connects most directly to how disability coverage fits into a financial plan.
Required monthly benefit = fixed monthly obligations + essential living costs − other income sources
| Expense line | Example household |
|---|---|
| Housing (mortgage/rent + tax + insurance) | $2,100 |
| Utilities and internet | $280 |
| Groceries | $750 |
| Transportation | $400 |
| Insurance premiums (health, auto, life) | $620 |
| Minimum debt payments | $450 |
| Childcare or dependent care | $900 |
| Total essential outflow | $5,500 |
| Less: spouse or other income | −$1,500 |
| Benefit needed | $4,000/month |
For this household, a $4,000 monthly benefit is the number — which happens to equal 60% of an $80,000 salary. If you are the only earner in the household, this is the method that matters most; a single-income household faces a different arithmetic when there is no second salary to absorb the shortfall. When all three methods converge, you can apply with confidence. When they diverge, the expense method should win, because it reflects what a disability would actually cost you.
Worked examples across income levels
| Gross annual income | 60% monthly benefit | Est. annual premium, 90-day wait, to 65 | Est. annual premium, 30-day wait, to 65 |
|---|---|---|---|
| $40,000 | $2,000 | $450–$750 | $600–$950 |
| $60,000 | $3,000 | $700–$1,150 | $900–$1,450 |
| $80,000 | $4,000 | $950–$1,550 | $1,250–$1,950 |
| $120,000 | $6,000 | $1,450–$2,300 | $1,850–$2,900 |
| $200,000 | $9,000–$10,000 (often capped) | $2,400–$3,700 | $3,000–$4,600 |
Self-employed readers should note that documented income rather than revenue sets the ceiling — the 1099 version of this calculation explains how Schedule C net profit changes the number.
Figures assume a professional/desk occupation class, non-smoker, age 35–40, own-occupation definition, and a major carrier. Manual occupations, hazardous hobbies, and existing health conditions all move the number upward, sometimes dramatically. State availability and carrier appetite vary.
The insurer’s cap: why you cannot buy 100%
Every carrier publishes a participation limit — the maximum monthly benefit it will issue relative to your income. The limits typically look like this:
| Annual income band | Typical maximum monthly benefit | Effective replacement |
|---|---|---|
| Under $60,000 | $3,000–$3,500 | 60%–70% |
| $60,000–$100,000 | 60%–65% of monthly income | 60%–65% |
| $100,000–$200,000 | $6,000–$11,000 | 50%–65% |
| $200,000–$500,000 | $10,000–$20,000 | 30%–55% |
| Above $500,000 | $20,000–$30,000, often requires financial underwriting | Under 50% |
High earners face a structural problem: the replacement percentage falls as income rises, so the absolute gap between what a policy pays and what a household spends grows with income. That gap is normally filled with a combination of group LTD, an individual policy, and a personal reserve — and it is why financial underwriting (tax returns, financial statements) becomes part of the application above certain benefit levels.
How the elimination period changes the math
The elimination period is your lever for trading premium against liquidity. Moving from 30 to 90 days typically reduces the premium by 15% to 25% — but only makes sense if you can fund three months of expenses from savings.
| Elimination period | Relative premium | Cash you need on hand | Best for |
|---|---|---|---|
| 30 days | 100% (baseline) | 1 month of expenses | Thin savings, single income, commission-based pay |
| 60 days | 88%–93% | 2 months | Most salaried workers with a small emergency fund |
| 90 days | 75%–85% | 3 months | Households with a 3–6 month reserve |
| 180 days | 65%–75% | 6 months | High earners with strong savings and group STD as a bridge |
The most common mistake here is choosing a 180-day elimination period to save premium while having only six weeks of savings — which converts a well-priced policy into one that never pays when you need it.
Should you add the cost-of-living rider?
A COLA rider increases the monthly benefit during a long claim, typically by 3% to 6% a year, and adds roughly 15% to 25% to the premium. For a policy with a benefit period running to age 65, it is usually worth it: a $4,000 benefit paid flat for 25 years loses more than half its purchasing power. For a 2-year benefit period, the rider rarely justifies its cost.
Review the number every three years
The benefit amount that fit at 32 does not fit at 40, after a promotion, a mortgage, and two children. Revisit the calculation when any of these change: income up or down by 20% or more, a new mortgage or major debt, a change in marital status, a new dependent, or a change in employer coverage. Most carriers allow benefit increases without full re-underwriting up to a stated limit, which is worth asking about at purchase rather than at claim time. For the definitions behind each policy term used on this page, start with what disability insurance coverage actually is.
Frequently asked questions
How much disability insurance do I need if I earn $80,000?
A common target is $4,000 a month, which is 60% of $80,000. Verify it against your fixed obligations first: if your essential monthly outflow is $5,500 and you have no other income, $4,000 leaves a $1,500 gap that has to come from savings or a spouse’s earnings. The expense method is the one that tells you whether 60% is actually enough.
Can I buy more than 60% of my income in disability coverage?
Rarely from a single carrier. Most cap participation at 60%–70% of gross income, and some carriers will consider a higher percentage only when the benefit is taxable or when group coverage is being coordinated. Stacking multiple individual policies to exceed the cap is generally not permitted, because carriers check with the MIB and with each other during underwriting.
Is the benefit taxable?
It depends on who paid the premiums. If you paid with after-tax dollars — as with an individual policy or an employer plan where the premium is deducted post-tax — benefits are generally tax-free. If your employer paid the premium and did not include it in your taxable wages, benefits are taxable as ordinary income. This is why a tax-free 60% is often worth more than a taxable 70%.
Should I count my spouse’s income when calculating the benefit?
Yes. The benefit needs to cover the household’s essential outflow, not your entire previous income. If a spouse earns $1,500 a month, the required benefit drops by that amount. Conversely, if you are the sole earner, the benefit needs to cover 100% of essential expenses — which may exceed the 60% replacement guideline and is a legitimate reason to apply at the carrier’s maximum.
What happens if I have group LTD and an individual policy?
Most individual policies coordinate with group coverage, meaning the individual benefit is reduced by what the group plan pays. The practical value of the individual policy in that setup is not the monthly percentage but the cap: group LTD usually stops at $5,000–$15,000 a month regardless of income, and an individual policy raises the ceiling. Check the “other income offset” clause before buying to avoid paying for coverage that will be fully offset.
Does a raise mean I should increase my coverage?
Usually yes, once income rises by 20% or more. Most carriers offer a future increase option that lets you raise the benefit without new medical underwriting, exercised at specified intervals or on documented income increases. If you did not buy that rider at issue, you may face full underwriting to increase later — which is the main argument for adding it when you are young and healthy.
How much does a $5,000 monthly benefit cost?
For a 35–40 year old in a professional occupation with a 90-day elimination period and coverage to age 65, expect roughly $1,100–$1,800 a year. A $5,000 monthly benefit corresponds to about $100,000 of annual income at a 60% replacement rate, so the premium lands near 1.1%–1.8% of income — consistent with the industry rule of 1%–3%.
Is it better to have a longer benefit period or a higher monthly benefit?
Higher monthly benefit, in most cases. A disability that lasts longer than two years is statistically less common than one that lasts three to twelve months, and the monthly amount is what determines whether you can pay your bills during the period you are most likely to face. Once the monthly benefit covers essential expenses, extend the benefit period — in that order.
Leave a Reply