Introduction
Disability insurance coverage and income protection are two of the most important but often misunderstood components of personal financial planning. While many people focus on life insurance or retirement savings, they overlook the risk of losing income due to illness or injury. In reality, a long-term disability can be financially devastating without proper protection in place.
This guide explains how disability insurance coverage works, what income protection insurance means, the differences between policy types, and how to choose the right plan for your needs. It is designed to help individuals, families, and self-employed workers make informed financial decisions in 2026.
What Is Disability Insurance Coverage?
Disability insurance coverage is a type of insurance that replaces a portion of your income if you become unable to work due to illness, injury, or medical conditions. It ensures you continue receiving payments even when your earning ability is temporarily or permanently affected.
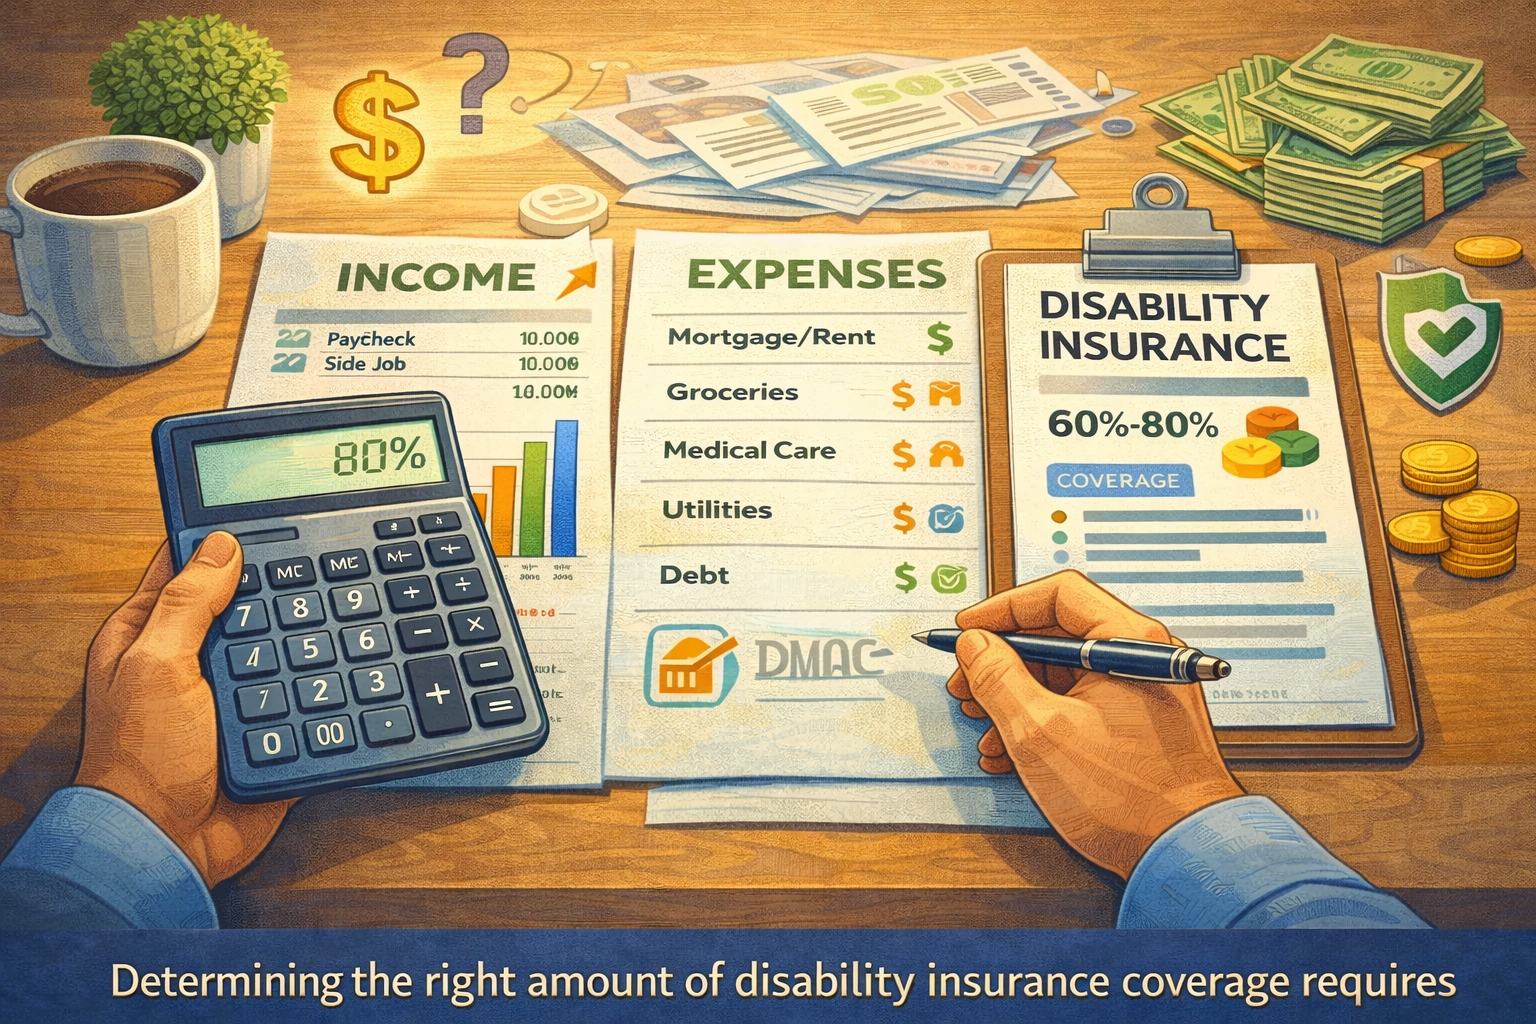
Typically, disability insurance pays between 50% and 80% of your regular income, depending on the policy.
There are two main types:
1. Short-Term Disability Insurance (STD)
Short-term disability insurance covers temporary conditions such as:
- Recovery from surgery
- Pregnancy and childbirth complications
- Minor injuries or illnesses
Coverage usually lasts from 3 months to 12 months.
2. Long-Term Disability Insurance (LTD)
Long-term disability insurance applies to more serious conditions, such as:
- Cancer
- Severe back injuries
- Chronic illnesses
- Neurological disorders
LTD benefits may last several years or even until retirement age, depending on policy terms.
What Is Income Protection Insurance?
Income protection insurance is a broader financial product designed to replace lost income when you cannot work due to medical reasons. While similar to disability insurance, it is often more flexible.
Income protection policies may cover:
- Partial disability (reduced ability to work)
- Mental health conditions (depression, anxiety)
- Rehabilitation periods
- Gradual return-to-work scenarios
Unlike strict disability insurance, income protection focuses on maintaining financial stability rather than only covering total inability to work.
Key Differences Between Disability Insurance and Income Protection
Although these terms are often used interchangeably, they are not exactly the same.
Coverage Scope
- Disability insurance: focuses on total or severe inability to work
- Income protection: includes partial disability and broader scenarios
Flexibility
- Disability insurance: more rigid definitions
- Income protection: more adaptable to real-life conditions
Payment Structure
- Disability insurance: fixed monthly benefit
- Income protection: may adjust based on reduced earnings
Eligibility Requirements
- Disability insurance: stricter medical definitions
- Income protection: more inclusive underwriting
Understanding these differences helps you choose the right level of financial protection.
Why Disability Insurance Coverage Is Important
Many people underestimate the likelihood of becoming disabled during their working years. However, statistics show that a significant portion of workers will experience a disability lasting more than three months before retirement.
Without disability insurance coverage, the consequences may include:
- Loss of steady income
- Accumulation of debt
- Difficulty paying rent or mortgage
- Depletion of savings
- Financial dependence on family members
Disability insurance acts as a financial safety net, ensuring stability during uncertain times.
Who Needs Income Protection Insurance?
Income protection insurance is especially important for:
1. Employees without employer coverage
Many companies do not provide adequate disability benefits.
2. Self-employed individuals
Freelancers, contractors, and gig workers have no automatic income safety net.
3. High-risk occupations
Jobs involving physical labor, construction, or transportation carry higher injury risks.
4. Primary earners
Households relying on a single income source are particularly vulnerable.
Even office workers and remote employees can benefit from coverage due to risks such as chronic illness or mental health conditions.
How Disability Insurance Works
Understanding the mechanics of disability insurance helps you evaluate policies effectively.
Step 1: Apply for Coverage
You provide personal, medical, and employment information.
Step 2: Underwriting Process
Insurance providers assess risk based on:
- Health history
- Age
- Job type
- Income level
Step 3: Policy Activation
Once approved, coverage begins after a waiting period.
Step 4: Filing a Claim
If disability occurs, you submit medical documentation.
Step 5: Benefit Payments
After approval, you receive monthly payments until recovery or policy expiration.
Common Features of Income Protection Policies
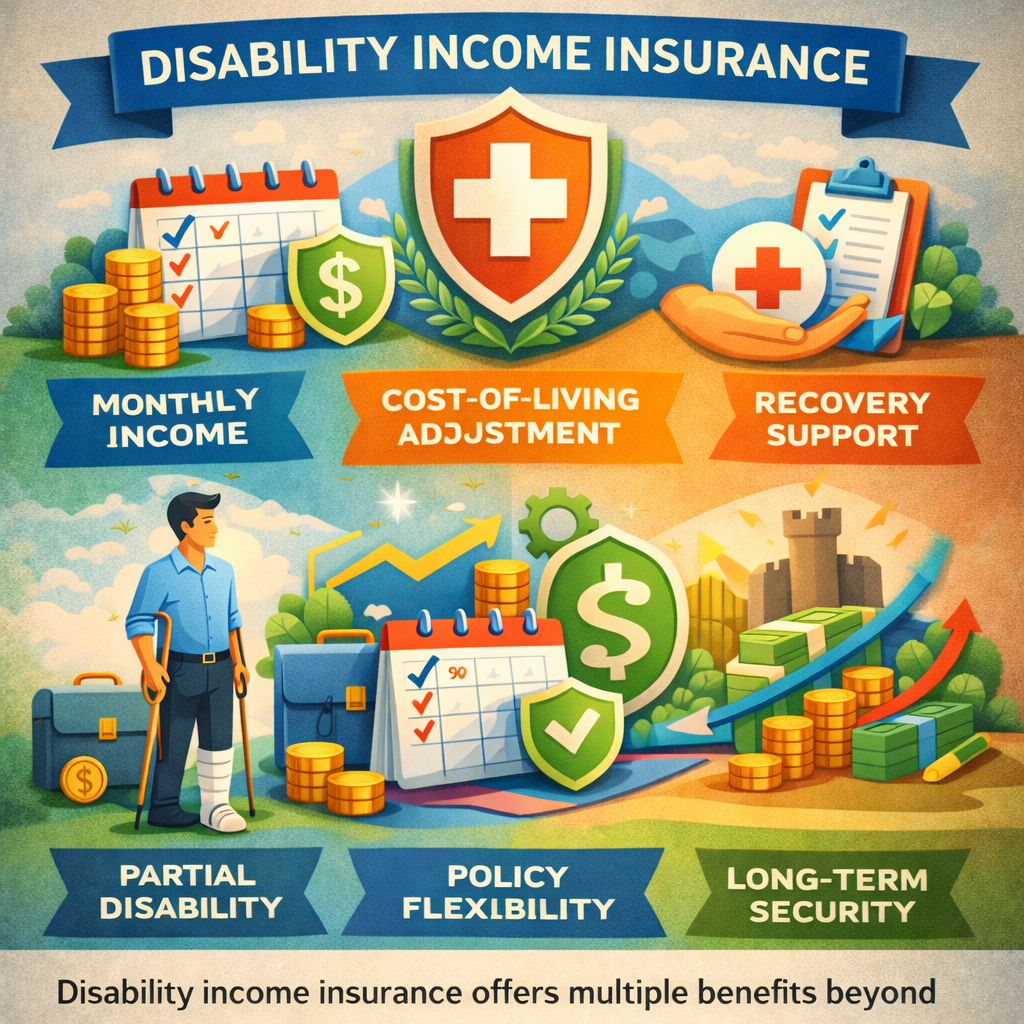
Modern income protection plans often include:
- Waiting period (elimination period): 30 to 180 days before benefits start
- Benefit period: 1 year, 2 years, 5 years, or until retirement
- Partial disability support: payments even if you return to work part-time
- Inflation protection: benefits increase over time
- Rehabilitation support: coverage for retraining or job transition
These features make income protection highly adaptable.
Factors Affecting Insurance Cost
The cost of disability insurance coverage depends on several factors:
1. Age
Younger individuals generally pay lower premiums.
2. Occupation
High-risk jobs increase insurance costs.
3. Health status
Pre-existing conditions may raise premiums or limit coverage.
4. Coverage amount
Higher monthly benefits result in higher premiums.
5. Waiting period
Longer waiting periods usually reduce monthly costs.
Tips for Choosing the Right Policy
When selecting disability insurance or income protection coverage, consider the following:
- Compare multiple providers before purchasing
- Check what conditions are excluded
- Understand waiting and benefit periods
- Choose coverage that replaces at least 60–70% of your income
- Look for policies with partial disability protection
- Read policy terms carefully before signing
A well-chosen policy can significantly reduce financial stress during difficult times.
The Future of Income Protection Insurance
In 2026, income protection insurance is evolving rapidly due to:
- Remote work trends
- Increasing mental health awareness
- AI-based risk assessment
- Digital insurance platforms
- Personalized coverage models
Insurers are now offering more flexible and user-friendly plans tailored to modern work lifestyles.
Conclusion
Disability insurance coverage and income protection insurance are essential tools for safeguarding financial stability. While disability insurance focuses on replacing income during severe incapacity, income protection offers broader and more flexible coverage options.
Whether you are an employee, freelancer, or business owner, having the right protection ensures that unexpected health issues do not turn into long-term financial crises.
Investing in the right policy today can provide peace of mind and financial security for the future.
Occupation Class: The Biggest Price Lever You Cannot Change
Two applicants, same age, same income, same benefit – one pays $180 a month and the other $420. The difference is occupation class, a five- or six-tier ranking that reflects claim frequency and duration for the work you actually do.
Classes are assigned by the insurer, not chosen – but they can be appealed with a job description.
| Class | Typical occupations | Relative premium | Claim profile |
|---|---|---|---|
| 6 (best) | Surgeons, anesthesiologists, attorneys | 0.6-0.8x | Low frequency, long duration when severe |
| 5 | Dentists, CPAs, architects, engineers | 0.8-1.0x | Moderate frequency, hand and back claims |
| 4 | Teachers, sales managers, pharmacists | 1.0-1.3x | Balanced frequency and duration |
| 3 | Nurses, technicians, supervisors | 1.3-1.7x | Higher frequency; lifting and shift work |
| 2 | Skilled trades, drivers, mechanics | 1.7-2.3x | High frequency; musculoskeletal dominated |
| 1 (worst) | Roofers, laborers, heavy construction | 2.3-3.0x+ | Very high frequency; limited benefit periods |
Premium per $100 of Monthly Benefit
This is the only honest way to compare disability quotes. It normalizes for benefit amount and lets you see what the definition and riders actually cost:
Monthly premium per $100 of monthly benefit, 90-day elimination period, non-smoker.
| Age at issue | Class 5, own-occ to 65 | Class 3, own-occ 5 years | Class 3, any-occ to 65 |
|---|---|---|---|
| 30 | $0.95 | $1.60 | $0.85 |
| 35 | $1.15 | $1.95 | $1.05 |
| 40 | $1.45 | $2.40 | $1.30 |
| 45 | $1.90 | $3.10 | $1.70 |
| 50 | $2.55 | $4.10 | $2.25 |
| 55 | $3.40 | $5.40 | $3.00 |
What Moves Your Price, in Order of Impact
- Occupation class – a two-class difference can double the premium and is worth appealing with a detailed job description.
- Age at issue – roughly 5-7% per year of age after 35; buying at 38 instead of 45 saves 30-40% for the life of the policy.
- Definition and duration – own-occ to 65 costs 45-70% more than any-occ to 65, and buys the coverage that matters for specialists.
- Elimination period – 30 to 90 days cuts roughly 20-30%; 90 to 180 cuts another 15-20%.
- Riders – COLA and residual are the two that usually earn their cost; the rest are situational.
- Tobacco use and build – tobacco can add 25-50%; height/weight outside the build chart adds a rating.
How to Appeal an Occupation Classification
- Request the class assignment in writing – it is usually disclosed on the illustration, not the quote email.
- Submit an employer job description listing duties, hours sitting/standing, lifting requirements and travel.
- If your title sounds physical but your duties are supervisory, say so with specifics: “I supervise 12 technicians and perform no installations.”
- Ask the broker to shop the same profile with two other carriers – class assignment varies by insurer.
- Re-check the class at each policy anniversary if your duties change; a reclassification can lower the premium permanently.
Frequently Asked Questions
What is an occupation class in disability insurance?
A risk tier from 1 to 6 assigned to your job based on claim frequency and duration. Class 6 is the cheapest (surgeons, attorneys) and class 1 the most expensive (heavy labor), with premiums differing by up to five times.
Can I change my occupation class?
Not by request, but you can appeal with a detailed job description showing your actual duties. Insurers also reclassify at renewal if your role changes significantly.
Why is own-occupation coverage so much more expensive?
Because it pays when you cannot perform your specific job, which is a much easier test to meet than any-occupation. The premium reflects that higher expected claim rate – typically 25-45% more.
Does age at purchase matter that much?
Yes – premiums rise roughly 5-7% per year of age after 35. Buying at 38 rather than 45 typically saves 30-40% for the life of a non-cancelable policy.
What is the cheapest way to buy meaningful coverage?
A 90-day elimination period, own-occupation for five years rather than to 65, no COLA, and the longest benefit period you can afford. That combination usually beats a cheaper any-occupation policy.
Do women pay more for disability insurance?
Sometimes, for certain ages and occupations, because claim incidence differs. Several states restrict gender-based pricing, so the effect varies by where you live.
Leave a Reply